Brochure
An overview of the index complete with strategy highlights and performance information
Download PDF


Stock market exposure built from a dynamic multi-factor approach. Bond exposure that responds to changes in market conditions. Daily, adaptive allocations seek to mitigate wild swings in the market. All delivered in a single, comprehensive package.
Stock exposure adjusts to the current economic regime by selecting companies with qualities suited for potential outperformance, while maintaining diversification across varying market environments.
Strategically allocates between long-term bonds and cash to adapt to changing market conditions.
Exposure to stocks, bonds, and cash adjusted daily seeking to provide a consistent volatility profile of 5%.
Dynamic multifactor strategy seeks to take advantage of changing market environments using a disciplined approach to determine the current economic regime and then increase exposure to factors that tend to be rewarded in that climate while decreasing exposure to those that do not, in order to seek to deliver better returns than generic stock market exposure:
Macro Regimes Framework
Emphasis on each factor is determined by the current environment.
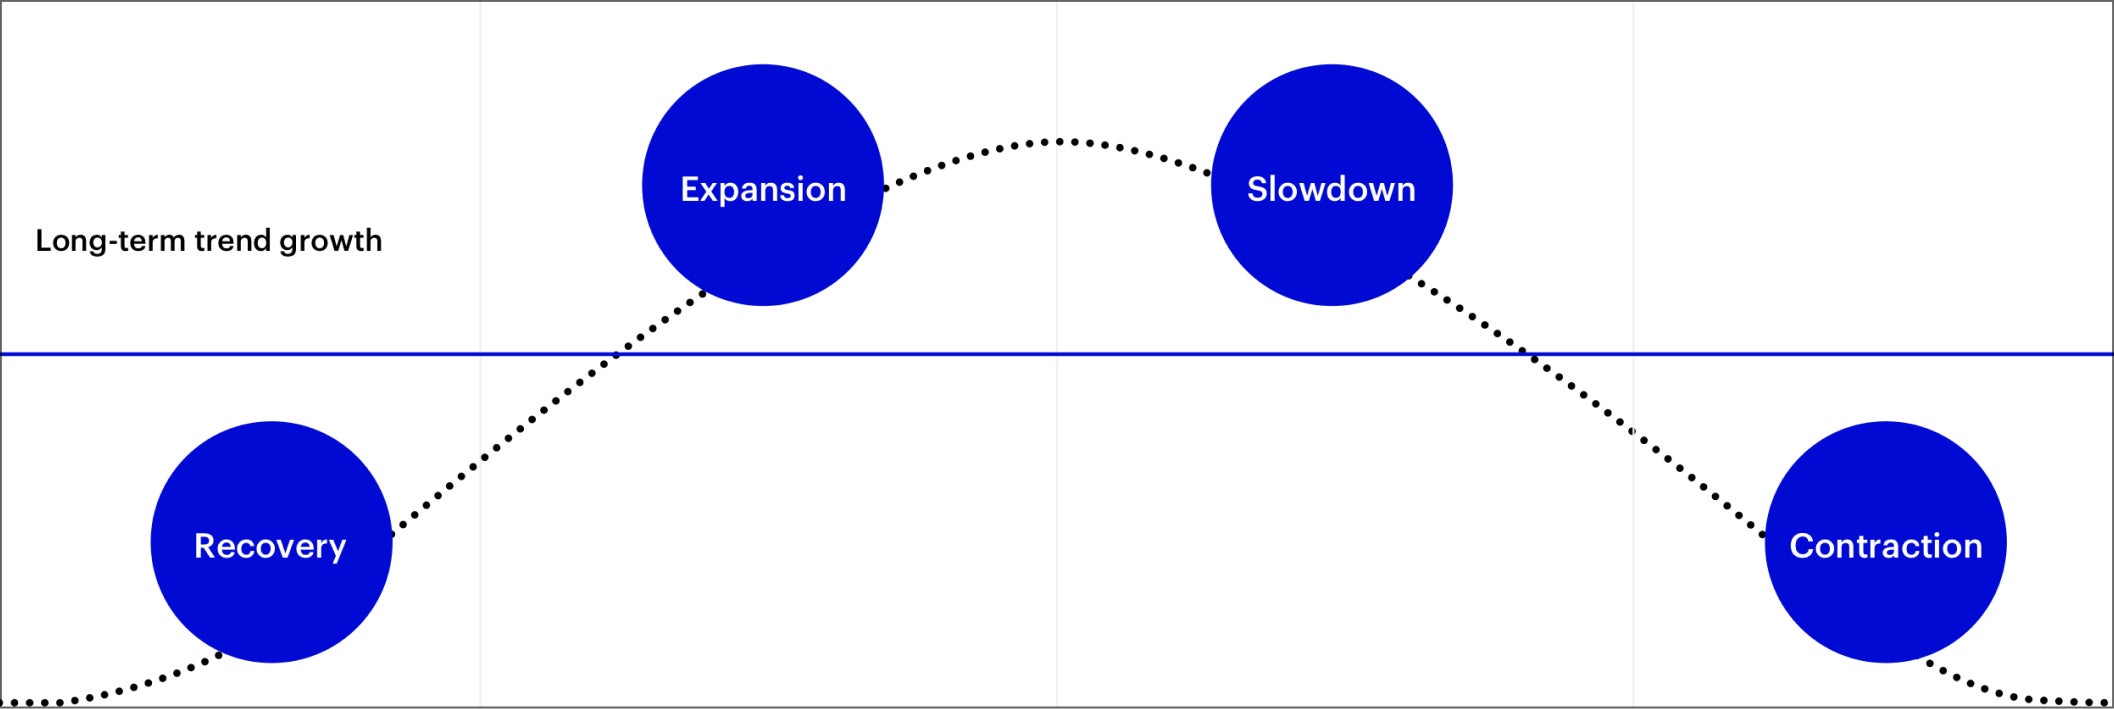
This diagram shows the four distinct regime periods of recovery, expansion, slowdown, and contraction and which factor tilts correspond with each regime.
| Recovery | Expansion | Slowdown | Contraction | |
|---|---|---|---|---|
| Long-term economic growth trend | Growth is below trend and accelerating | Growth is above trend and accelerating | Growth is above trend and decelerating | Growth is below trend and decelerating |
| Size | X | X | ||
| Value | X | X | ||
| Momentum | X | X | ||
| Low volatility | X | X | ||
| Quality | X | X |
Uses a rules-based approach that assigns securities a score for each investment style: Value, Momentum, Quality, Low Volatility and Size. Security weights are then tilted in a rules-based manner based on the factors most relevant to the current economic regime. For illustrative purposes only.
In addition to multi-factor equity, the Invesco Dynamic Growth Index also provides exposure to bonds when conditions warrant as an additional and complementary source of returns. Beneficially, bonds – and, in particular, US Treasury bonds – quite often experience less dramatic swings in returns relative to stocks.1
In most market environments, bond exposure in the index comes from exposure to 10-year Treasury bonds, which, historically, have delivered stronger returns than cash.2
However, a drop in price coupled with higher volatility in 10-year Treasuries often signals a rise in interest rates. When this happens, the index allocates a portion of the bond exposure away from 10-year Treasuries and into cash, potentially offering more price stability under these conditions. The goal is to provide more defensive exposure and help cushion the impact of declining bond prices.
Exposure to stocks, bonds, and cash are adjusted daily seeking to deliver a smoother performance profile for the Invesco Dynamic Growth Index over time. For instance, when the riskiness of stock holdings rises, the index will shift away from stocks and into bonds, into cash or into a combination of bonds and cash. On the other hand, as the riskiness of stock holdings decreases, the index will shift away from bonds or cash and into stocks.
Additionally, as the riskiness of the combined allocation of stocks and bonds rises and falls, the index allocates more and less, respectively, to cash.
In periods of high volatility, it may be possible for the index to be comprised heavily or fully of bonds and / or cash, which may persist as volatility is elevated. Due to excess return index construction, cash allocations in the index are non-remunerated.4
The centerpiece of the Invesco Dynamic Growth Index is a dynamic multi-factor approach. Value, Momentum, Quality, Low Volatility and Size are stock characteristics, or factors, shown by academics and practitioners to deliver more attractive returns historically than the broad market:3
Attractively priced stocks tend to outperform those that are expensive
Factor metrics:
Cash flow, earnings and sales multiples
Trends in recent company stock performance tend to continue
Factor metrics:
Recent stock performance
Well-run companies in a position of financial strength tend to be rewarded
Factor metrics:
Profitability, leverage ratio
Investor biases often lead them to overpay for attention-grabbing stocks with lottery-like payoffs as compared to low-volatility stocks
Factor metrics:
Recent stock performance
Small companies tend to perform better than larger companies
Factor metrics:
Market capitalization
An overview of the index complete with strategy highlights and performance information
Download PDF
Rules and guidelines followed to build and maintain the index
Download PDF
Information on the Invesco Dynamic Growth Index
Download PDF
NA5169172
The Bloomberg U.S. Trsy Bellwether 10-Year TR Index is part of the Bloomberg US Treasury Bellwether Index Family, which tracks the on-the-run (Most recently issued) US Treasury securities for specific maturities. The 10-year TR Index represents the total return (price change + reinvested cash) of the most recently issued 10-year US Treasury note.
The Bloomberg U.S. Trsy Bellwether 3-Month TR Index is part of the Bloomberg US Treasury Bellwether Index Family, which tracks the on-the-run (Most recently issued) US Treasury securities for specific maturities. The 3-month TR Index measures the total return of the most recently issued 3-month US Treasury bill, reflecting price movements and interest accrual.
There is no assurance that the index discussed in this material will achieve its investment objectives.
There is no guarantee the stated volatility target will be achieved.
Forward-looking statements are not guarantees of future results. They involve risks, uncertainties and assumptions. There can be no assurance that actual results will not differ materially from expectations.
Diversification/Asset allocation cannot eliminate the risk of fluctuating prices and uncertain returns and does not assure a profit or protect against loss.
Factor investing is an investment strategy in which securities are chosen based on certain characteristics and attributes that may explain differences in returns. Factor investing represents an alternative and selection index based methodology that seeks to outperform a benchmark or reduce portfolio risk, both in active or passive vehicles. There can be no assurance that performance will be enhanced or risk will be reduced for strategies that seek to provide exposure to certain factors. Exposure to such investment factors may detract from performance in some market environments, perhaps for extended periods. Factor investing may underperform cap-weighted benchmarks and increase portfolio risk. There is no assurance that the index discussed in this material will achieve their investment objectives.
Holding cash or cash equivalents may negatively affect performance.
Although bonds generally present less short-term risk and volatility than stocks, the bond market is volatile and investing in bonds involves interest rate risk; as interest rates rise, bond prices usually fall, and vice versa. Bonds also entail issuer and counterparty credit risk, and the risk of default. Additionally, bonds generally involve greater inflation risk than stocks.
This does not constitute a recommendation of any investment strategy or product for a particular investor. Investors should consult a financial professional before making any investment decisions.
Invesco Indexing LLC is the benchmark sponsor of the index and is an indirect, wholly owned subsidiary of Invesco Ltd. The group is legally, technologically, and physically separate from other business units of Invesco, including the various global investment centers.
Solactive AG (“Solactive”) is the calculation agent and the administrator in accordance with the Principles for Financial Benchmarks published by the International Organization of Securities Commissions in July 2013 of Invesco Dynamic Growth Index (the “Index”). The financial instrument that is referencing the Index is not sponsored, endorsed, promoted, sold or supported by Solactive in any way and Solactive makes no express or implied representation, guarantee or assurance with regard to: (a) the advisability in investing in the financial instruments; (b) the quality, accuracy and/or completeness of the Index; and/or (c) the results obtained or to be obtained by any person or entity from the use of the Index. Solactive does not guarantee the accuracy and/or the completeness of the Index and shall not have any liability for any errors or omissions with respect thereto.
The information and data provided is for informational purposes only and is compiled from sources believed to be reliable; however, accuracy, completeness, timeliness, or continued availability cannot be guaranteed. All information is provided “as is,” without warranty of any kind, and may include data or content supplied by third parties over whom Invesco has no control and which has not been independently verified. Invesco and its affiliates are not responsible or liable for any calculations, errors, or omissions related to third‑party content, data, benchmarks, or index components.
This link takes you to a site not affiliated with Invesco. The site is for informational purposes only. Invesco does not guarantee nor take any responsibility for any of the content.