Multi Asset 2026 Insurance Midyear Investment Outlook
Risk assets have held up in 2026, but we believe tight credit spreads, geopolitical risks and inflation uncertainty mean insurers should stay cautious heading into the second half.
This newsletter brings the latest topics impacting insurers, aimed to help those managing investment portfolios while considering an insurer’s business, regulatory and solvency needs.
For this third edition of Invesco Insurance Insights, we examine how insurers can look beyond traditional fixed income allocations through selective exposures to private market and structured credit solutions as they seek to enhance portfolio outcomes. Within this context, we focus on AAA collateralized loan obligations (CLOs), examining their structural features, investment characteristics, and potential role within portfolios. Using a hypothetical fixed income portfolio, we assess how an allocation to AAA CLOs may influence portfolio outcomes (from both economic and risk-based capital perspectives) while also touching upon broader use cases, including access through ETF wrappers.
As always, we hope you find this of interest and please do not hesitate to reach out to us.
Jaijit Kumar, Head of Asia Insurance Solutions
Hello everyone.
My name is Jaijit Kumar and I cover insurance solutions for Asia here at Invesco.
Joining me today is Derek Fin from a private credit team.
Welcome, Derek.
Thanks, Jaijit
So insurers in the region have been looking at private credit for quite some time.
It's an area of focus for them, not least a way to diversify their existing credit exposure, but also the yield return pick up from the illiquidity and complexity premium.
But one other area that a lot of insurers have been looking at is structured credit, notably CLOs
So just wanted to get your take on that and you know, if you can run us through what's kind of the difference between CLOs and your typical private credit, if you will?
Yeah, I think it's the right question to ask because there's been a lot of noise and a lot of headlines in private credit recently.
And it's very easy to just think about it in one asset class format.
We like to think of it as 2 segments.
One is the illiquid side of private credit, whether it's corporate direct lending or distress credit.
And the other cohort is the liquid side of private credit.
So broadly syndicated loans, as you mentioned, structured products, CLOs that falls under an asset class that's more similar to traditional fixed income.
So all the attributes you know, for traditional bonds, whether it's daily liquidity, daily mark to market pricing, public ratings, those are all the same characteristics you get in something like CLOs.
So to your point, we've seen more and more interest towards the more liquid side, particularly in the higher quality part of the segment in AAA CLOs.
I'm curious from your perspective and having conversations with CLOs and insurers, how do insurance companies think about CLOs as an asset class?
Yeah, that's certainly interesting.
And you're exactly to your point that you know, these two have public ratings.
So the focus for insurers generally tends to be on the senior tranches.
So the AAA and the AA rated tranches.
Obviously they're getting the high credit rating, they're getting potential kind of yield pickup and so on.
And also back to the point about diversification, they're possibly getting exposure to kind of a subset bank loans in this case, which they may not have, but in a sort of disciplined and structured manner with a fair amount of cushion to kind of absorb any downgrades or defaults.
So very attractive from that perspective.
The only point to note is really for, you know, these are obviously floating rate notes.
And so they don't necessarily do a lot for ALM (Asset Liability Management), especially for the life insurance portfolios unless you pair them with kind of interest rate swap or something.
But you know, for general insurance portfolios, for example, these can work as they are.
So it tends to be more of kind of a yield enhancement play and certainly sticking to kind of the more secure the higher rated areas of the structure.
Right, that makes sense.
In the third edition of Insurance Insights, Jaijit Kumar and Derek Fin explore the growing role of CLOs in insurer portfolios. They discuss how CLOs differ from traditional private credit investments and examine the key considerations that make CLOs an increasingly relevant asset class for insurance companies.
Hello everyone.
My name is Jaijit Kumar and I cover insurance solutions for Asia here at Invesco.
Joining me today is Derek Fin from a private credit team.
Welcome, Derek.
Thanks, Jaijit
So insurers in the region have been looking at private credit for quite some time.
It's an area of focus for them, not least a way to diversify their existing credit exposure, but also the yield return pick up from the illiquidity and complexity premium.
But one other area that a lot of insurers have been looking at is structured credit, notably CLOs
So just wanted to get your take on that and you know, if you can run us through what's kind of the difference between CLOs and your typical private credit, if you will?
Yeah, I think it's the right question to ask because there's been a lot of noise and a lot of headlines in private credit recently.
And it's very easy to just think about it in one asset class format.
We like to think of it as 2 segments.
One is the illiquid side of private credit, whether it's corporate direct lending or distress credit.
And the other cohort is the liquid side of private credit.
So broadly syndicated loans, as you mentioned, structured products, CLOs that falls under an asset class that's more similar to traditional fixed income.
So all the attributes you know, for traditional bonds, whether it's daily liquidity, daily mark to market pricing, public ratings, those are all the same characteristics you get in something like CLOs.
So to your point, we've seen more and more interest towards the more liquid side, particularly in the higher quality part of the segment in AAA CLOs.
I'm curious from your perspective and having conversations with CLOs and insurers, how do insurance companies think about CLOs as an asset class?
Yeah, that's certainly interesting.
And you're exactly to your point that you know, these two have public ratings.
So the focus for insurers generally tends to be on the senior tranches.
So the AAA and the AA rated tranches.
Obviously they're getting the high credit rating, they're getting potential kind of yield pickup and so on.
And also back to the point about diversification, they're possibly getting exposure to kind of a subset bank loans in this case, which they may not have, but in a sort of disciplined and structured manner with a fair amount of cushion to kind of absorb any downgrades or defaults.
So very attractive from that perspective.
The only point to note is really for, you know, these are obviously floating rate notes.
And so they don't necessarily do a lot for ALM (Asset Liability Management), especially for the life insurance portfolios unless you pair them with kind of interest rate swap or something.
But you know, for general insurance portfolios, for example, these can work as they are.
So it tends to be more of kind of a yield enhancement play and certainly sticking to kind of the more secure the higher rated areas of the structure.
Right, that makes sense.
Using a hypothetical fixed income portfolio, we examine the portfolio-level implications of allocating to AAA CLO allocations from both economic and risk-based capital perspectives. We also explore how CLO ETFs may provide insurers with cost-efficient, liquid and diversified market access.
Risk assets have held up in 2026, but we believe tight credit spreads, geopolitical risks and inflation uncertainty mean insurers should stay cautious heading into the second half.
Invesco’s Capital Market Assumptions (CMAs) are updated on a regular basis and incorporate the latest market developments.
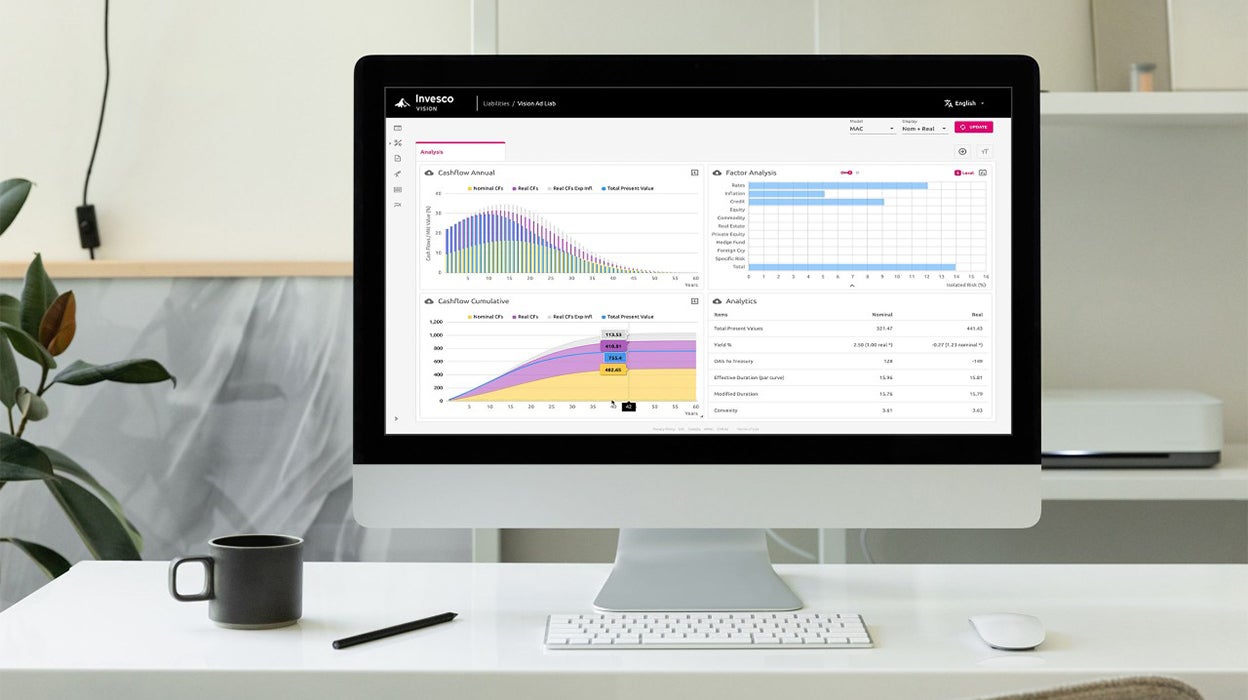
This newsletter explores a bottom-up approach to fixed income portfolio efficiency. Leveraging our proprietary analytics platform, Invesco Vision, we demonstrate how insurers can build more resilient and optimized portfolios.
The resilient global economy presents insurers with opportunities in high-quality bonds and selective equities. Elevated yields support income, while diversification may help manage risks amid geopolitical and policy uncertainty.
Invesco Solutions is proud to present our 2026 Capital Market Assumptions providing the long-term estimates for over 170 major asset classes to aid in strategic and tactical asset allocation decisions.
For APAC insurers, investment grade CLO tranches — especially AAA-rated — offer a practical way to increase yield, manage risk, and diversify portfolios.
The Vision platform is a state-of-the art, portfolio diagnostics tool to “pre-experience” how different variables affect investment outcomes. By identifying risk and return drivers, including under certain risk-based capital regimes, as well as exposures to an array of factors, Vision effectively characterizes the inherent risks in a defined liability or cash flow profile to identify optimal investment strategies.
Request Vision Demo
Request a demonstration of the complimentary portfolio management research and analytics service.